This Content Is Only For Subscribers
Most landlords know the rent amount without looking it up. Ask for the real monthly profit and the answer usually takes longer. That is normal. Rent is one number. Profit is the result of several numbers working together.
Here is how I would calculate it for a small rental in DFW and North Texas.
Step One: Start With Collected Rent
Begin with the rent the property is expected to collect, then make room for vacancy instead of assuming twelve perfect months every year.
If a house rents for $2,000 a month, I would not underwrite it as though the full $24,000 will always arrive without interruption. Even a good property eventually has a turnover, a delayed move in, or a period of make ready work.
For illustration, if you hold back 5 percent for vacancy, the $2,000 monthly rent becomes about $1,900 of effective monthly revenue for planning purposes.
Step Two: Add the Fixed Costs
Next, convert the big annual bills into monthly numbers. Property taxes, landlord insurance, HOA dues, and any owner paid recurring services belong here.
If the annual property tax bill is $6,000, that property carries a $500 monthly tax cost whether you pay the bill once a year or escrow it every month. If insurance is $2,400 a year, add another $200 a month.
This step matters in Texas because taxes and insurance can move enough to change the economics of a deal. I would update these numbers every year rather than keep using the figures from the day the property was purchased.
For properties with insurance renewals coming up, I would use the current renewal quote rather than last year’s premium. The same goes for taxes. Profit calculations get stale quickly when the largest fixed costs are allowed to sit unchanged on an old spreadsheet.
Step Three: Average the Ordinary Repairs
Routine maintenance is less predictable, so use history. Look at the last twelve months of repairs, lawn care, pest control, small plumbing calls, and other ordinary property expenses. Divide the total by twelve.
If you spent $3,600 over the last year, use $300 a month in your calculation. One month may be $50 and another may be $900. The average keeps the profit number honest.
If you have owned the property for less than a year, use the best actual information you have and stay conservative. Seller records can help, but your own operating style may produce different costs. One landlord handles lawn care. Another pushes that responsibility to the tenant. One owner replaces aging equipment early. Another repairs it longer. Those choices change the monthly profit.
I would also separate true recurring maintenance from one time turnover work. A full repaint after a long tenancy is different from a normal service call. You still need to budget for both, but keeping the categories separate makes it easier to see where the property is actually consuming money.
Step Four: Fund Future Replacements
This is the line item that turns a landlord calculation into an investor calculation. The roof, HVAC system, water heater, appliances, and flooring all have a remaining life. You do not need to predict the exact failure date. You do need to acknowledge that replacement is coming.
If your numbers suggest the property should be setting aside $200 to $300 a month for future replacements, put that amount into the calculation before you call anything profit.
For DFW and North Texas rentals, I would be especially conservative with cooling equipment because long heat stretches can expose weak systems quickly. I would also watch roof age, hail history, irrigation, drainage, and signs of foundation movement because those costs can move from manageable to expensive faster than many owners expect.
Step Five: Subtract Debt Service
After operating costs and reserves, subtract the mortgage payment. The principal portion builds equity, but the full payment still leaves your bank account each month. If you are trying to measure spendable cash flow, use the full debt service amount.
If you pay for professional management, include that too. If you self manage, I would at least track your time so you know whether the apparent savings are real. It does not have to appear in the same cash flow line, but it belongs in the investment decision.
Put the Whole Example Together
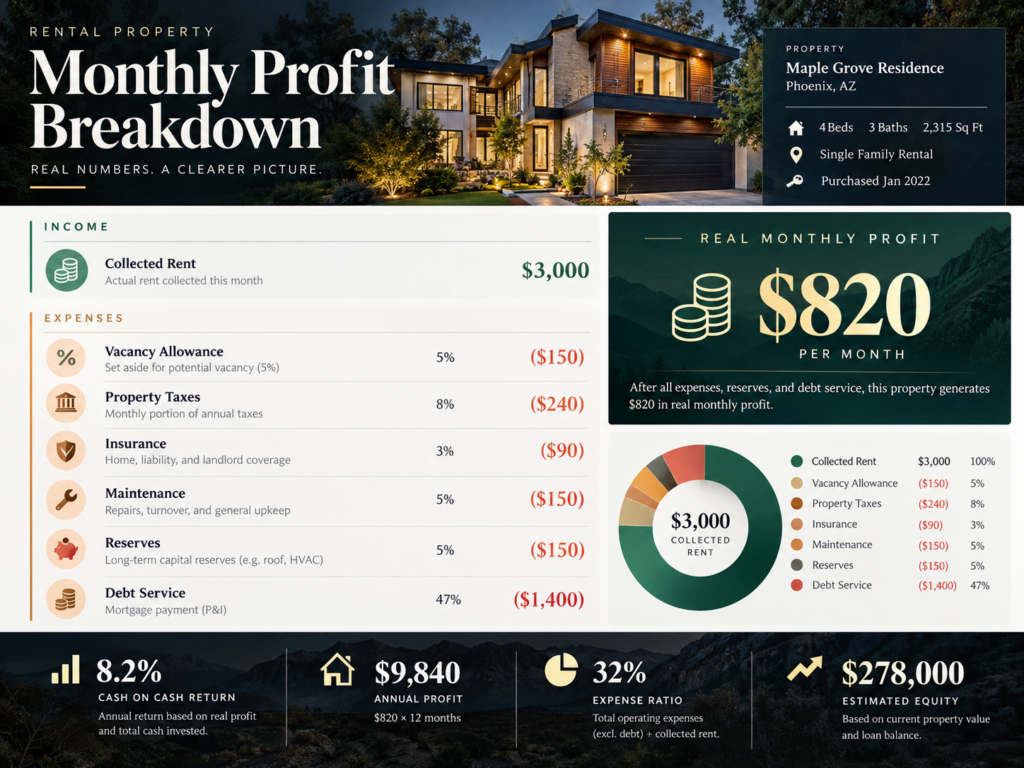
Take a property renting for $2,000 a month. After a 5 percent vacancy allowance, use $1,900 in effective revenue. Assume $650 for taxes, insurance, and HOA costs, $250 for ordinary maintenance, $200 for future capital replacements, and $1,050 for debt service.
That leaves negative $250 in monthly cash flow. It may still be building equity and appreciating, but it is not producing positive spendable cash flow under those assumptions. That is useful information, even if it is not the answer you hoped to see.
Now change the assumptions and see how sensitive the deal is. If the rent is $100 higher, the loss narrows. If insurance rises by $100 a month, it gets worse. If the mortgage is paid off, the property may become strongly cash flow positive. That is why a real monthly profit calculation is useful. It shows which numbers are doing the work.
I would run this calculation on every property at least once a year and again before a renewal, refinance, major renovation, or sale decision. In North Texas, I would also revisit it after a large insurance renewal, a major hail claim, or a foundation repair because those events can change the economics quickly. The goal is not to admire the spreadsheet. The goal is to know what the property is actually contributing to the portfolio.
A Number You Can Actually Use
I would rather own a property that honestly makes $250 a month than one that supposedly makes $600 until the next major repair arrives. Real profit is not the biggest number you can justify. It is the number that still holds up after vacancy, repairs, reserves, taxes, insurance, and debt are all given a seat at the table.