This Content Is Only For Subscribers
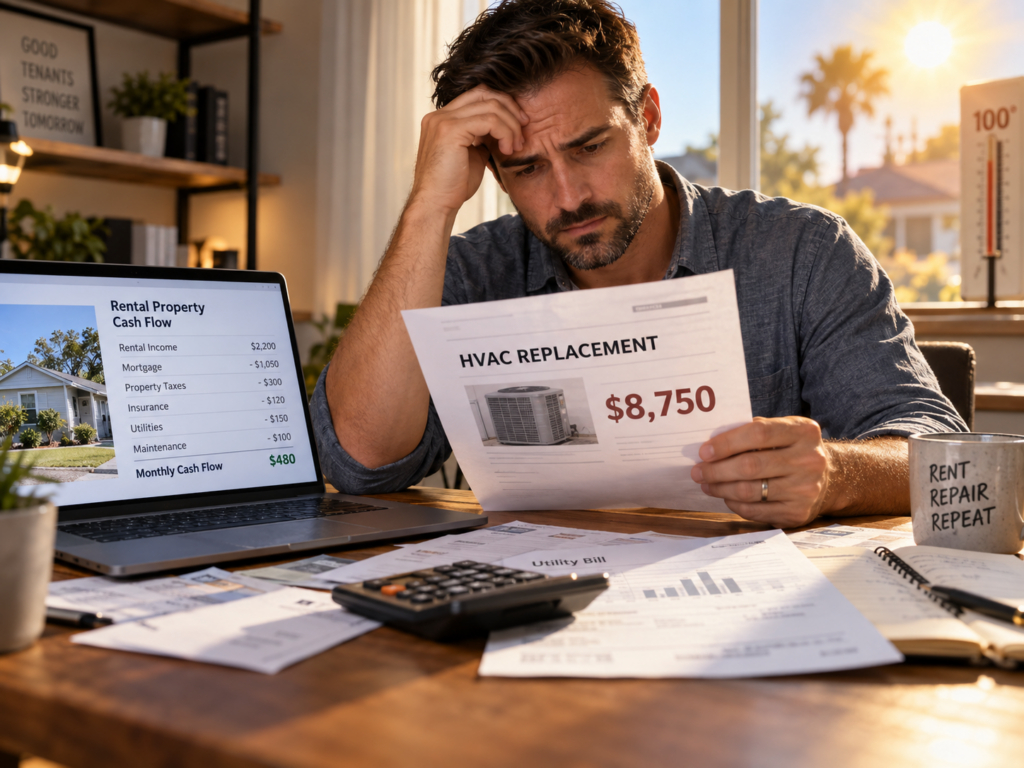
A North Texas landlord collects $1,950 in rent and has $1,450 going out each month for the mortgage, taxes, insurance, and routine bills. On paper, the property looks like it makes $500 a month. Then the HVAC system fails during a long stretch of summer heat and the replacement costs $7,500. More than a year of that supposed cash flow is gone in one repair.
The repair did not suddenly make the property a bad investment. It exposed a problem in the way the profit was being calculated.
Surplus Is Not the Same as Profit
There is a useful distinction here. Monthly surplus is what is left after the bills that happened to arrive this month. Profit is what is left after you account for the full cost of owning the property, including expenses that show up only every few years.
That is why a rental can look great for ten quiet months and terrible in month eleven. The roof, air conditioner, water heater, flooring, and plumbing are wearing out every month whether they send you an invoice or not.
If you ignore that wear until something breaks, the earlier months look artificially strong. The big repair simply catches the books up with reality.
Why One Repair Can Eat So Much Cash
Large repairs hurt small landlords because the income is steady while the expenses are lumpy. Rent arrives in pieces. Capital expenses often arrive all at once.
Timing makes it worse. In DFW and North Texas, air conditioning failures tend to show up when systems are under the most stress and contractors are already busy. A hailstorm can damage a roof or condenser across an entire neighborhood at once, and a hard freeze can create plumbing calls faster than local vendors can absorb them.
Older homes in Dallas, Fort Worth, Arlington, and other established North Texas neighborhoods can add another layer. A property may have updated flooring and paint while still carrying older plumbing, electrical components, roofing, or mechanical equipment behind the walls. The cosmetics look new. The expensive systems may not be.
There is also a regional issue investors sometimes miss: distance. A rental near central Dallas or Fort Worth may have several vendors willing to respond quickly. A house farther out in Frisco, McKinney, Denton, Prosper, Weatherford, or another surrounding market may fall outside a vendor’s normal service area or carry a longer trip charge. That does not make the property a bad investment. It means the repair budget needs to reflect where the house actually sits.
The same applies after widespread hail, severe thunderstorms, or a hard freeze. Roofers, HVAC technicians, electricians, plumbers, and restoration crews can all get busy at the same time. Prices and response times can move together. A reserve sized only for calm conditions may feel thin when many owners are calling the same vendors at once.
Run the Repair Math Before the Repair
The answer is not to guess which system will fail next. The better approach is to charge the property for future repairs every month.
Suppose the property produces a $500 monthly surplus before reserves. If the age of the systems suggests you should be setting aside $250 a month for future repairs and replacements, then I would treat the property as producing about $250 in usable monthly cash flow.
That number may be less exciting, but it is far more useful. It tells you what the investment can actually distribute without weakening itself.
I also like to review the reserve assumption once a year. If the HVAC system is another year older, if the roof has taken hail or wind damage, or if repeated foundation, plumbing, or drainage calls are starting to show a pattern, the monthly reserve should change with the property. A reserve number set five years ago should not automatically follow the house forever.
A Reserve Changes the Experience of the Repair
If you have been moving $250 or $300 into a dedicated reserve every month, a large repair still hurts. Nobody enjoys writing a $7,500 check. The difference is that the money has already been recognized as part of the cost of ownership.
You authorize the work, pay from the reserve, and rebuild the account. You are not carrying the repair on a high interest card or pulling money from personal savings.
That is a calmer way to own rentals. The expense still reduces your cash balance, but it does not force a new financing decision in the middle of a repair. You already made the financing decision gradually through the monthly reserve contributions.
The Repair Did Not Kill the Deal
When one repair wipes out a year of reported profit, I would not automatically blame the repair. I would go back to the original underwriting and ask whether the property was ever being charged enough for its own future expenses.
That is the investor lesson. A rental should pay you, but it should also pay for itself. The number that matters is what remains after both of those jobs are covered.